Storm season and a costly assumption
As the clocks prepare to go back and the first Atlantic storms of the season line up off the west coast, thousands of Irish homeowners are making an assumption that could cost them dearly: that their home insurance will pay out if water comes through the front door.
For most households, flood damage is included as standard in a home insurance policy. But for a significant minority, it is not. Some policies quietly exclude flood altogether, some carry an excess so high that cover is close to meaningless, and some homeowners cannot get flood cover at any price.
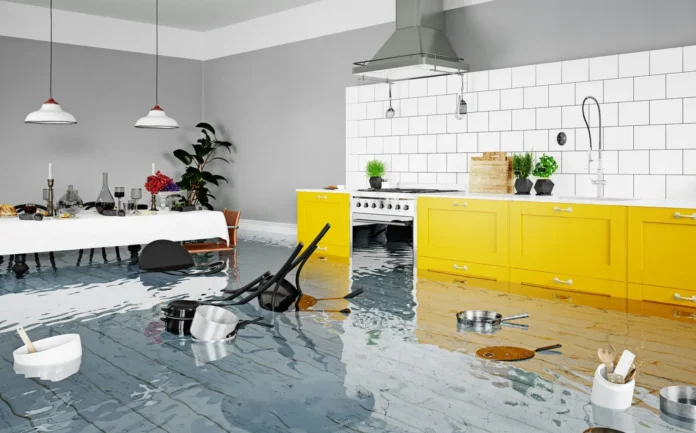
The scenes from Midleton during Storm Babet in October 2023, and the damage left behind by Storm Éowyn in January 2025, showed how quickly a house can go from dry to uninhabitable. For families without adequate cover, the cost of recovery falls on their own savings, on borrowing, or on emergency State support.
One in 20 homes struggle to get cover
The scale of the problem was set out by the Central Bank in its Flood Protection Gap report in October 2024. It found that roughly one in 20 buildings in Ireland has difficulty accessing flood insurance. That figure includes properties that cannot get cover at all, and those that can only get it at exceptionally high prices.
The Central Bank estimated that inland flooding from rivers and surface water costs about €101 million a year on average. A severe year could be far worse: it projected a loss of around €510 million roughly once every 25 years.
The gap is not confined to rural river towns. More than half of it is concentrated in five counties: Dublin, Cork, Kildare, Clare and Louth.
Even homes protected by State-funded flood defences are not guaranteed cover. Insurers and the Office of Public Works have an agreement intended to restore cover once defence schemes are completed. Yet in April of this year, a Tipperary TD said households in Clonmel were still being refused flood cover, or charged heavily loaded premiums, more than a decade after the town’s flood relief scheme was finished.
The risk is growing, and policy is catching up
The Central Bank’s report also warned that Ireland is likely to see significantly more rainfall in the future because of climate change. Researchers at Maynooth University have found that extreme flood events could happen twice as often, with north-western Europe, including Ireland, among the worst-affected regions.
The issue has moved up the political agenda this year. On 11 August, the Department of Finance set up a new Flood Insurance Protection Gap Working Group. It brings together Government departments, State agencies and insurers to look for practical ways to improve access to cover for homes and businesses in flood-risk areas.
Weeks later, Insurance Ireland published its own proposals. The most eye-catching was a levy of €24 a year on every insured household, which would fund a Sustainable Flood Insurance Fund for homes that cannot otherwise get cover. The industry body also called for a grant scheme to help homeowners make their properties more flood-resilient, and for flood performance certificates similar to the BER energy rating.
That idea appears to have public backing. A survey published by Allianz in August found that eight in 10 people support flood-risk certificates for homes, which would tell buyers about a property’s flood risk before they commit.
None of these measures will be in place for this winter, however. For now, the responsibility for checking cover rests with the homeowner.
What to check in your policy
Many people only read their policy documents after something has gone wrong. Before the worst of the winter weather arrives, it is worth taking 15 minutes to check the following.
- Is flood listed as an insured peril? Look in the policy schedule and the exclusions section, not just the summary. An endorsement added at renewal can remove flood cover without much fanfare.
- What is the flood excess? Some insurers apply a separate, much higher excess for flood claims. An excess of several thousand euro can make smaller claims pointless.
- Are buildings and contents both covered? Flood water damages floors, kitchens and wiring, but it also destroys furniture, appliances and personal belongings.
- How does the policy define flood? Rising river water, coastal storm surge, overwhelmed drains and rising groundwater may be treated differently.
- Is alternative accommodation included? A flooded home can take months to dry out and repair. Check the limit and how long the insurer will pay for.
If flood is excluded, ask your insurer why and whether cover could be restored. Installing flood-resilience measures such as non-return valves, raised sockets or flood barriers may help, so keep receipts and any engineer’s reports. Brokers can sometimes find specialist cover where mainstream insurers decline.
Anyone protected by a completed OPW scheme should tell their insurer, and ask specifically whether that protection has been taken into account. Homeowners who are unhappy with how a refusal or claim has been handled can complain to the insurer and, if that does not resolve it, to the Financial Services and Pensions Ombudsman.
Shop around before the storms arrive
The home insurance market does not treat flood risk uniformly. One insurer may exclude a property that another will cover, and flood excesses can vary widely between providers. Renewal is the natural point to compare, but there is no need to wait if your current policy leaves you exposed.
Comparing policies side by side makes it easier to see which insurers include flood cover, what excess applies, and whether contents and alternative accommodation are included. If you have not reviewed your cover in the past year, now is the time to get a quote for home insurance and make sure your policy matches the risk your home actually faces.
Government and industry may eventually close the flood protection gap. Until they do, the families most likely to recover quickly from a flood will be those who checked their cover before the water arrived.